September ended the third quarter with a slight pullback, even as the quarter delivered its first positive result since 2022.
Highlights:
- The average U.S. advertised asking rent fell $1 to $1,775 in September, while annual growth improved to 0.7%
- Third-quarter rent growth reached 0.3%, the first positive third-quarter result since 2022
- Matrix added total occupancy, which rose 50 basis points since January to 93.9%
- SFR-BTR advertised rents fell $4 to $2,245 but remained 0.8% above a year earlier
Annual growth broadens while renewals cool
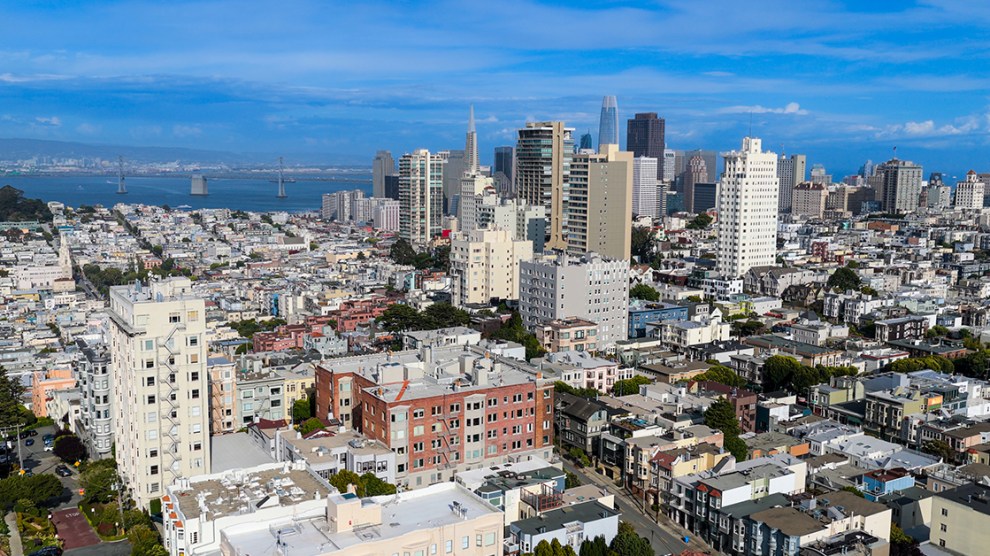
Year-over-year rent growth improved to 0.7% in September, led by Gateway and Midwest markets. San Francisco remained well ahead of the Matrix top 30 at 7.0%, followed by New York City (3.8%), Chicago (3.2%) and Kansas City (3.1%). At the bottom were Austin (-2.5%), Houston (-2.0%), Denver (-1.6%) and Tampa (-1.4%). The advertised-rent improvement contrasts with renewals. National renewal rent growth slowed to 1.7%, far below its 8.7% peak in early 2023. San Francisco remained an exception at 8.2%, while renewal growth turned negative in Austin (-4.3%) and Phoenix (-2.4%).
September rents declined 0.1% month-over-month, reversing the quarter’s positive direction, and 18 of the top 30 markets posted declines. Denver (-0.8%), Boston and New York City (-0.7% each) and Charlotte (-0.6%) recorded the largest drops. San Francisco (0.9%), Baltimore (0.8%) and Indianapolis (0.6%) led gains. Renter-by-Necessity rents rose 0.1%, while Lifestyle rents fell 0.1%.
Matrix now publishes total occupancy, including properties in lease-up, alongside stabilized occupancy. Stabilized occupancy was 94.3% in August, down 30 basis points year-over-year, while total occupancy was 93.9%, up 10 basis points. The total rate has gained 50 basis points since January, narrowing the gap with stabilized occupancy to 0.4 percentage points from 0.9 percentage points at its second-quarter 2025 peak.
A new lens on occupancy
Total occupancy rose 1.5 percentage points since January in Austin to 91.6% and 1.4 percentage points in Denver and Nashville to 93.3%. The lowest total occupancy rates among the top 30 were Houston (91.3%), Austin (91.6%), Dallas (92.0%) and Las Vegas (92.1%).
Single-family build-to-rent advertised rates fell $4 in September to $2,245, the first monthly decline since January, but annual growth improved to 0.8%. Occupancy was 94.9% in August, down 20 basis points year-over-year. Miami (6.2%), Cleveland (4.3%) and Kansas City (3.7%) led rent growth. San Antonio (-5.6%), Greenville and Houston (-2.6% each), Pensacola (-2.4%) and Phoenix (-1.8%) were weakest.
Read the full Yardi Matrix Multifamily National Market Report: September 2026.
Add Comment